





 Premium
LATAM Airlines is the largest airline group in Latin America. It came out of a pandemic-era bankruptcy with the strongest balance sheet in its history and has just posted record results, and it is now investing in a bigger fleet. Unusually for high yield, all three rating agencies have it on a positive outlook, and management has delivered on ambitious plans before.
Publication date: 14-08-2026
LATAM flies passengers and cargo across Latin America and the world, and most of its money comes from selling seats on its own network. It is the number-one domestic airline in four of its five home markets — 69.8% in Chile, 65.5% in Peru, 49.5% in Ecuador and 39.4% in Brazil — and runs the region's only global long-haul network. It is listed in Santiago and New York with a market capitalisation of about US$16.6bn.
LATAM earns its money in three ways:
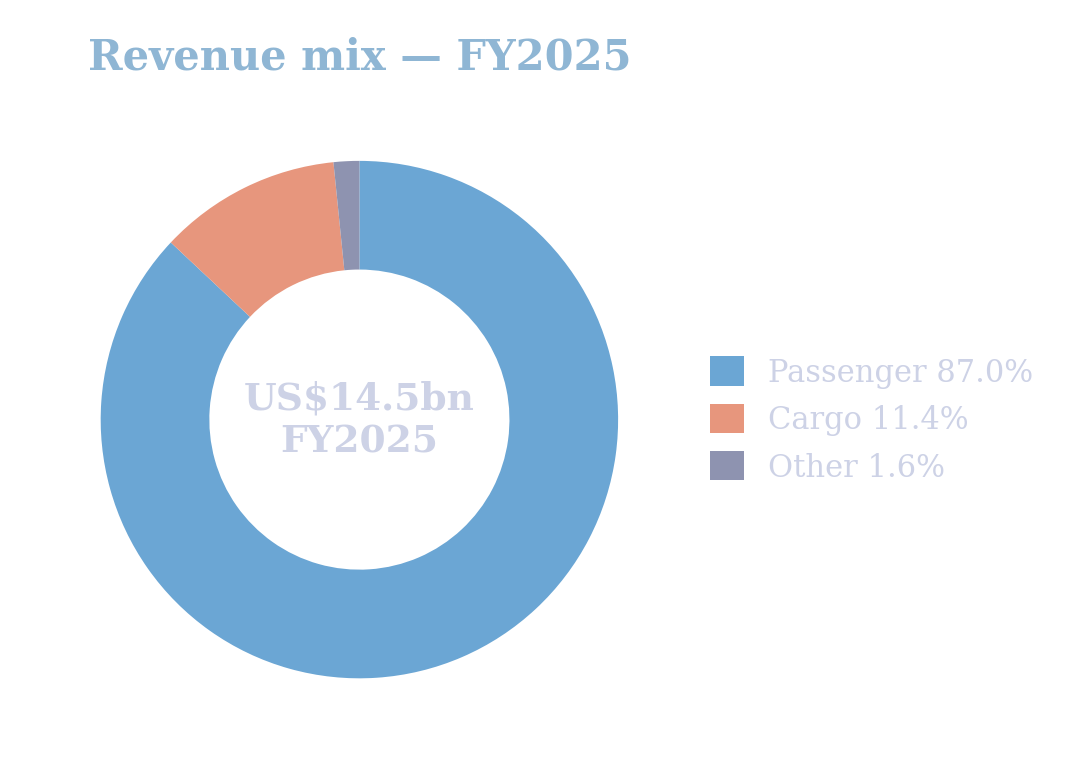
Passenger flying dominates the revenue mix. Source: LATAM IR historical spreadsheet, FY2025.
LATAM has just posted the strongest results in its history. First-half 2026 revenue reached US$8.3bn, up 24.6%, with adjusted EBITDA of US$2.0bn, and on a last-twelve-month basis the adjusted EBITDA margin was 26.7%, down from a record 28.2% in 2025 as margins pass their peak. Management guides 2026 to a 23–25% margin. The chart below puts the 2020 bankruptcy trough next to today's recovery.
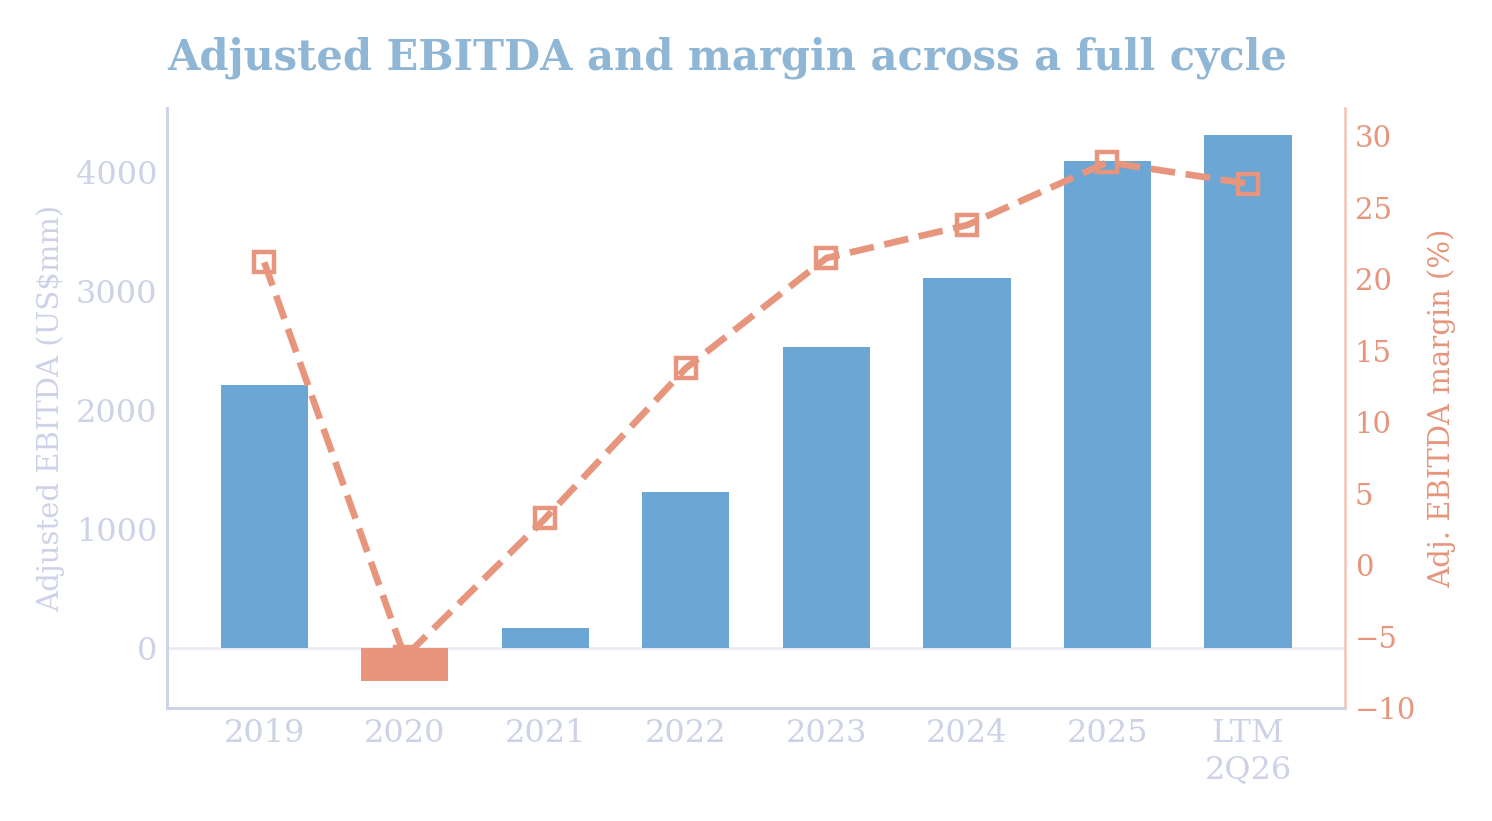
A full cycle in one picture: the 2020 trough, then record results in 2025. Source: LATAM IR historical series; 2Q26 release.
LATAM has delivered on an ambitious plan before. The pandemic cut revenue 58% in 2020 and pushed the company into U.S. Chapter 11 bankruptcy; it emerged in November 2022 with debts renegotiated, fleet costs cut by around 40%, and new strategic owners in Delta and Qatar Airways. It is that reset, rather than the recovery in travel, that explains today's figures — and it is now investing in a larger fleet, growing from 383 aircraft to a planned 452 by 2028, funded mostly from its own earnings so that debt rises only moderately.
The live risk is fuel and the Brazilian real, not the balance sheet. LATAM pays for fuel and aircraft in US dollars but earns a large part of its revenue in Brazilian reais, so the combination that hurts is expensive fuel and a weak real at the same time. The June 2026 quarter was the real-world test: the all-in jet fuel price jumped to US$194.5 per barrel and the fuel bill rose 93.1%, yet fares carried most of it and the company still held a 17.0% margin in its worst quarter.
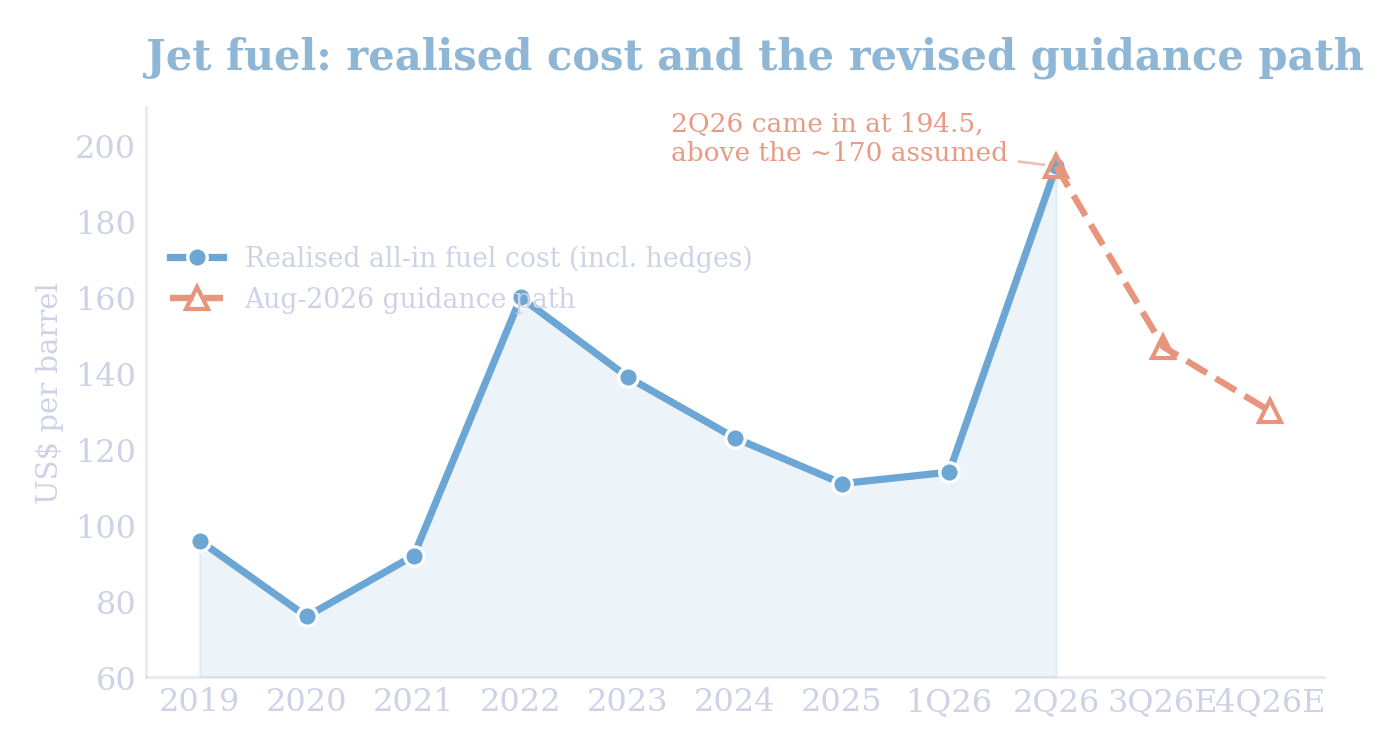
Jet fuel spiked to US$194.5/bbl in 2Q26, above guidance, and the margin still held. Source: 2Q26 release; company fuel series.
Debt is moderate today, and stays covered even in the downside. Net debt is US$6.4bn, about 1.5x EBITDA, and there is no bond to repay before 2030. In our deliberately harsh downside — fuel back near US$175 and a weak real through 2027 — leverage rises toward 2.4x in 2027 before falling back, and in no modelled scenario does the company run short of cash or miss a payment. The one event to plan around is a US$2.2bn refinancing wall in 2030–31, four years away; the company has already shown it can refinance, replacing 13.375% notes with this 7.625% issue in July 2025.
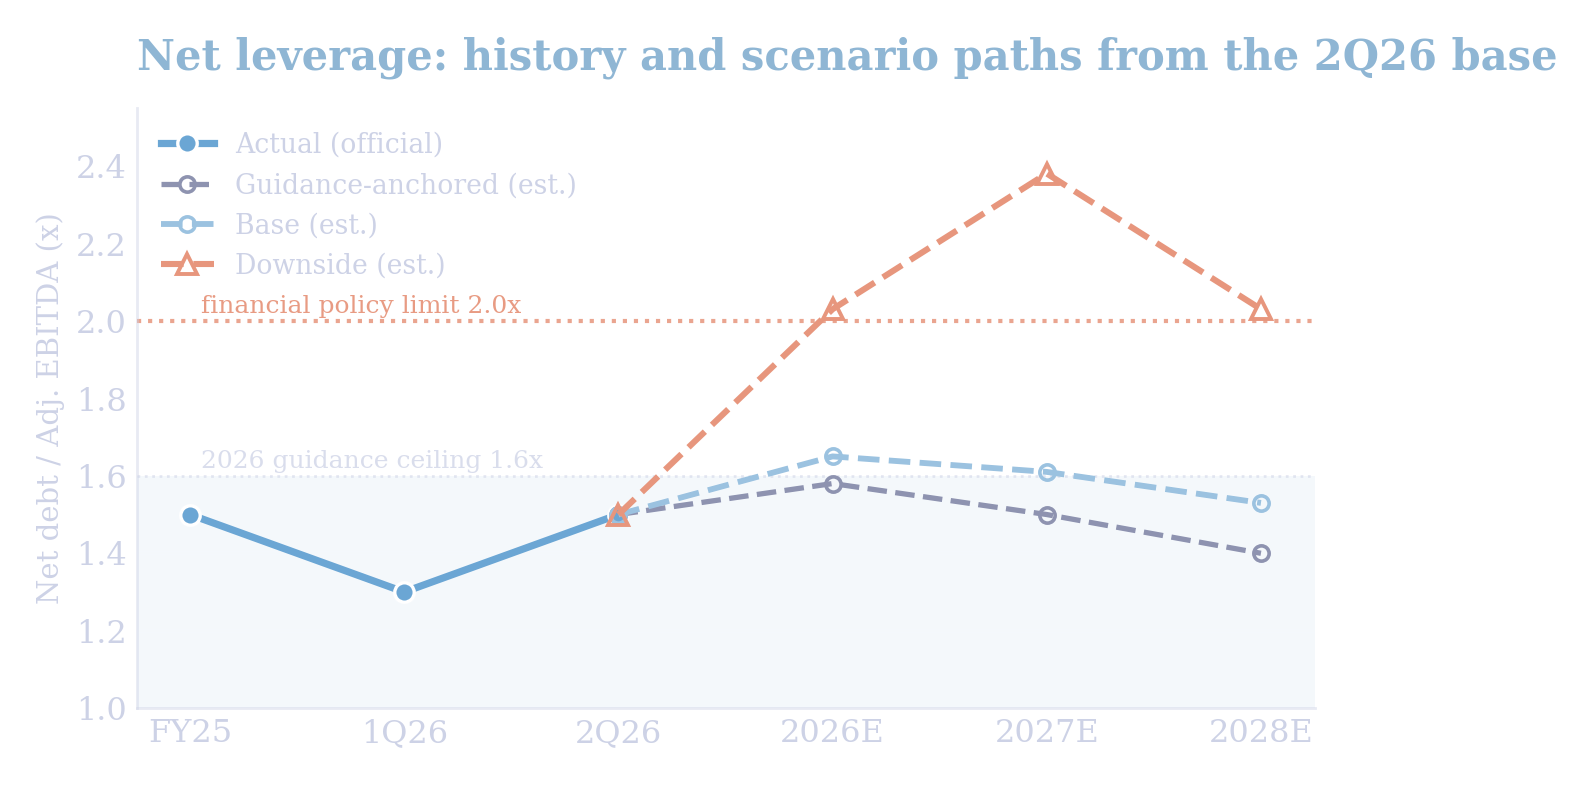
Even the downside peaks near 2.4x and turns back down. Source: 2Q26 release; Elqui scenario estimates.
The 7.625% notes are senior secured and mature in January 2031, with US$800mm outstanding. LATAM issued them in July 2025 to refinance more expensive debt. They are guaranteed by certain subsidiaries and secured mainly on the loyalty programme, the brand and the JFK and Heathrow slots, and they rank behind the revolving credit facilities once those are drawn. The bond can be repaid early from July 2027 at 103.813 — barely half a point above today's price — so the upside is capped and good news tends to mean early repayment rather than a rising price. Because the bond is in dollars, a euro-based investor also carries EUR/USD currency risk.
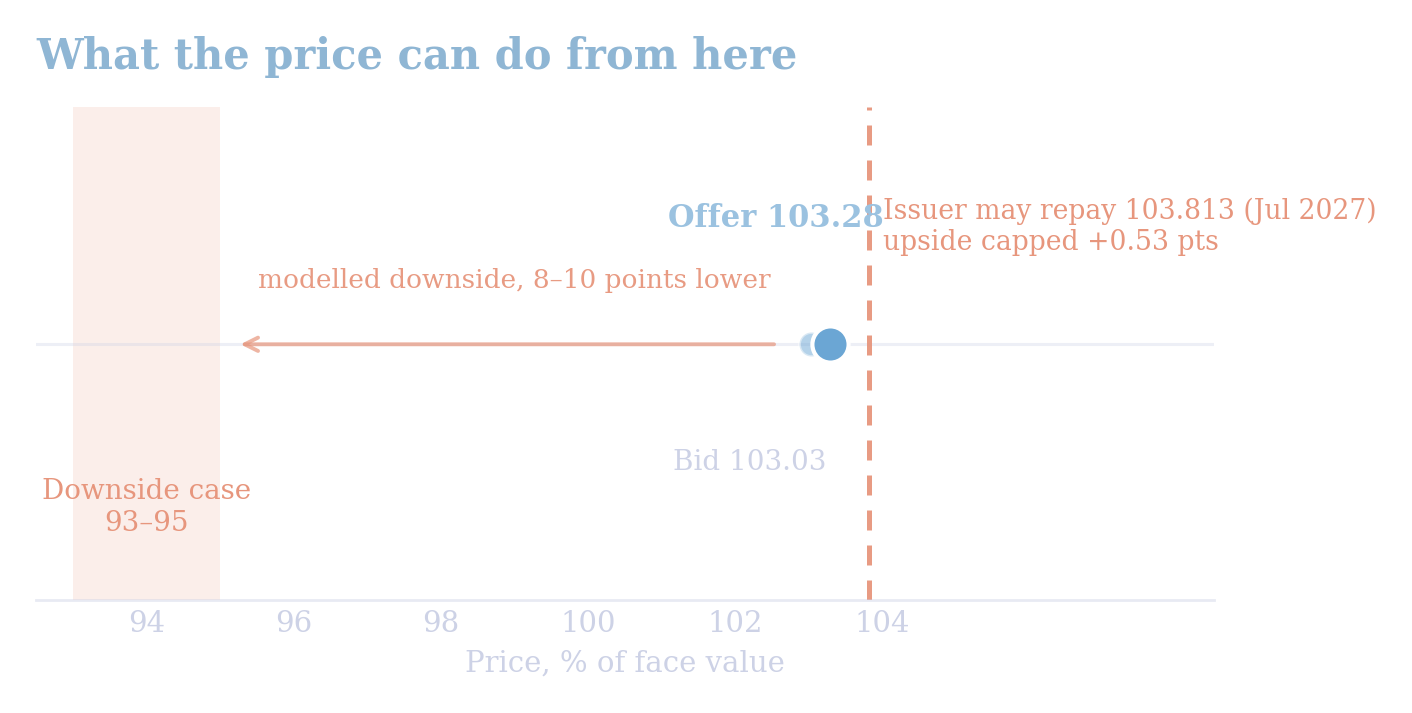
At 103.28 the bond sits just below the 103.813 call price.
Fitch rates the issuer BB, S&P rates it BB and Moody's rates it Ba2 — all with a positive outlook, and the notes themselves are rated BB+ by Fitch, one notch above the issuer. The positive outlooks reflect the recovery in earnings and the strong balance sheet; the risks the agencies watch are the fuel-and-currency exposure and the discipline of shareholder payouts, which resumed in 2025.
as of 30-06-2026, US$ bn
| Metric | Value | Metric | Value | Metric | Value |
|---|---|---|---|---|---|
| Assets | 19,6 | EBITDA Margin LTM | 26,7 % | Liquidity | 4,2 |
| Revenue LTM | 16,1 | Net debt | 6,4 | FCF LTM | 1,7 |
| EBITDA LTM | 4,3 | Net Debt/EBITDA | 1,5× | Equity | 2,0 |
| Net Profit LTM | 1,6 | EBITDA/Interest | 6,6× | Debt/Equity | 4,5× |
All data and information is provided “as is” for informational purposes only, and is not intended for trading purposes or financial, investment, tax, legal, accounting or other advice. Please consult your broker or financial representative to verify pricing before executing any trade. Bondfish is not an investment adviser, financial adviser or a broker. None of the data and information constitutes investment advice nor an offering, recommendation or solicitation by Bondfish to buy, sell or hold any security or financial product, and Bondfish makes no representation (and has no opinion) regarding the advisability or suitability of any investment. Mention of specific financial products or operations does not constitute an endorsement by Bondfish.
The financial products or operations referred to in such data and information may not be suitable for your investment profile and investment objectives or expectations. It is your responsibility to consider whether any financial product or operation is suitable for you based on your interests, investment objectives, investment horizon and risk appetite. Bondfish shall not be liable for any damages arising from any operations or investments in financial products referred to within. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision.
This data is not updated in real time and represents the prices available at the end of the previous trading day. Bondfish does not verify any data and disclaims any obligation to do so. Bondfish expressly disclaims the accuracy, adequacy, or completeness of any data and shall not be liable for any errors, omissions or other defects therein, delays or interruptions in such data, or for any actions taken in reliance thereon. Bondfish shall not be liable for any damages relating to your use of the information provided herein.
Past performance is not a reliable indicator of future results.